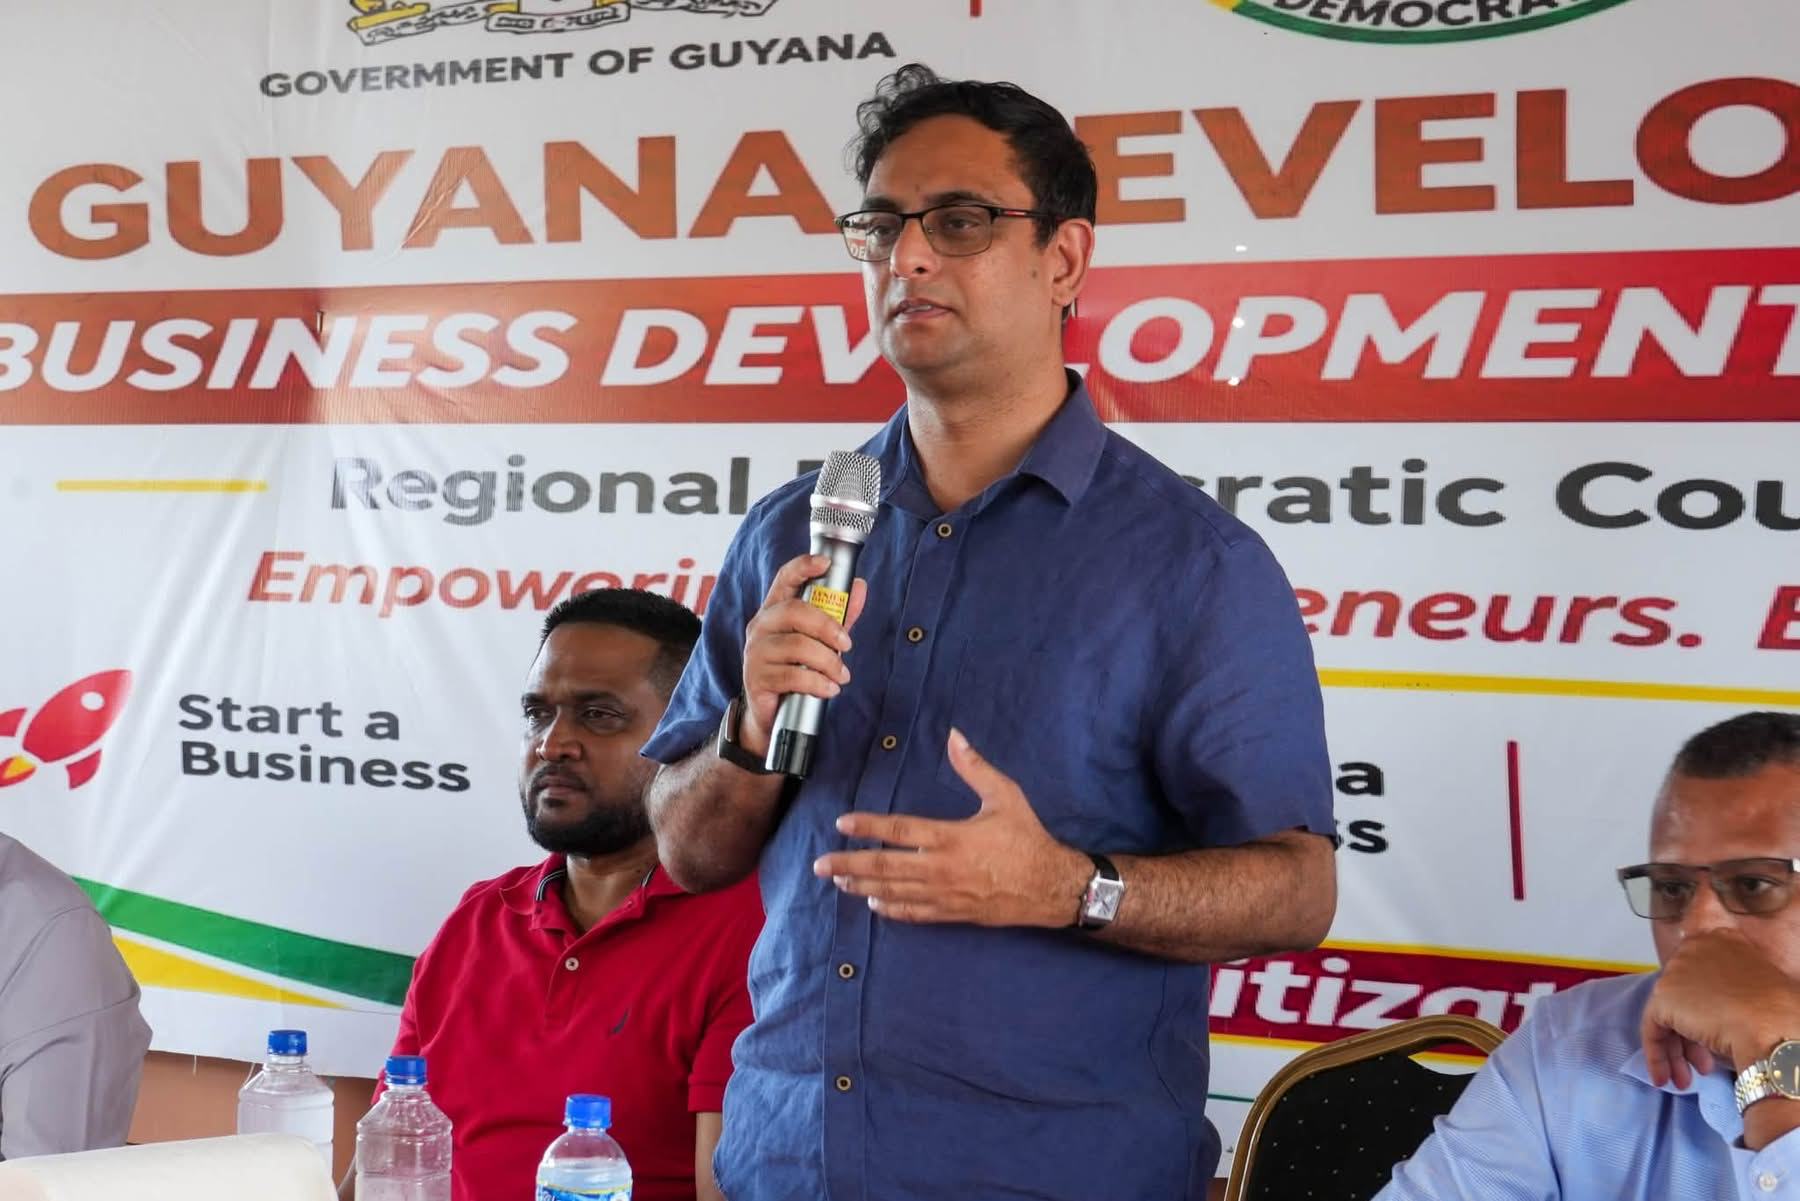
Photo: National Communications Network, Guyana.
State broadcaster NCN reported on 5 November that Public Service, Government Efficiency and Implementation Minister Zulfikar Ally hoped Guyana Development Bank applicants would be contacted within approximately 30 days. Speaking in Moruca, he said follow-up could include a request for additional information.
For a small-business owner waiting to buy equipment or stock, the distinction matters: a request for more information is not an approved loan, and an approval is not yet money available to spend. The report establishes an expectation about communication rather than a guaranteed lending or payout deadline.
Three milestones a business should keep separate
An application records a request for credit. A follow-up helps establish what information is available and what still needs clarification. A decision determines whether the lender will offer finance and on what terms.
The Government of Guyana's GDB service description sets out a sequence involving credit-officer review, an offer if approved, acceptance and eventual payment into the borrower's bank account. Its processing-time field says no time is specified.
That published process matters more to a purchasing decision than a headline about response speed. A business cannot safely equate an acknowledged submission with an offer, or an offer awaiting acceptance with completed disbursement.
For example, an entrepreneur considering a refrigerator for a food business can obtain a quotation while waiting. Entering a non-refundable purchase commitment before finance is confirmed creates a different obligation: the supplier may expect payment even if the lending request does not proceed as hoped. That is an illustrative commercial risk, not a reported GDB applicant's case.
The timing still needs a defined starting point
The new account leaves practical questions unanswered. It does not define whether the expected interval begins at initial submission, completion of all information or another stage. It also does not specify calendar versus working days, an enforceable service standard, or how applicants with earlier submissions are being handled.
Those omissions should not be filled with assumptions. A business whose application has been pending should not calculate a guaranteed outcome from a date that the bank has not defined for that purpose.
Applicants can instead keep their submission reference, the date they applied and copies of correspondence together. If contacted, they should clarify what is being requested, how to submit it securely and whether anything remains outstanding. These are record-keeping precautions, not additional eligibility rules announced by the bank.
Prepare for a useful conversation
For a business, responsiveness is not simply answering the telephone. The applicant should be able to explain the proposed use of funds, distinguish a firm supplier quotation from an estimate and show how the purchase relates to sales or operating capacity.
A short, consistent explanation is more useful than a larger request unsupported by the business's own figures. If costs have changed since submission, the applicant should be prepared to identify the change rather than present an old quotation as current.
Similarly, expected sales and confirmed orders should not be mixed together. A lender's request for clarification is an opportunity to make the proposal understandable; it should not be interpreted as an invitation to overstate demand or repayment capacity.
The official government directory identifies gdb.gov.gy as the bank's website. Applicants should start from that verified route and official correspondence, not advertisements or intermediaries offering guaranteed approval. If a message asks for further documents, they should verify the sender and the submission route before sharing sensitive records.
From demand to delivery
Invest Guyana has already covered the bank's launch and products, its early application demand and the credit-reporting framework. This update concerns a different question: how applicants move through the next communication stage.
For assessing delivery, the useful future measures are the number of complete applications, requests awaiting clarification, decisions, offers accepted and loans actually paid out. Those figures would make it possible to distinguish an active pipeline from completed financing. No new figures for those stages are established here.
The immediate message for an applicant is therefore practical: remain reachable, keep the business proposal accurate and wait for confirmed terms before treating expected financing as available cash. Faster communication can help a business plan, but it does not remove the lender's assessment or the borrower's need to make sound purchasing decisions.
Editor's note: This is a business-finance update, not personalised financial advice or a guarantee of lending. Information was checked on 6 November 2026.