Photo: Department of Public Information, Guyana.
A Canadian company considering a long-lived investment in Guyana may see the term “investment-protection agreement” and assume a new layer of legal protection is already available. A Guyanese enterprise seeking a Canadian partner may read the same announcement as confirmation that a bilateral economic agreement is on its way.
Both conclusions would move ahead of the official record.
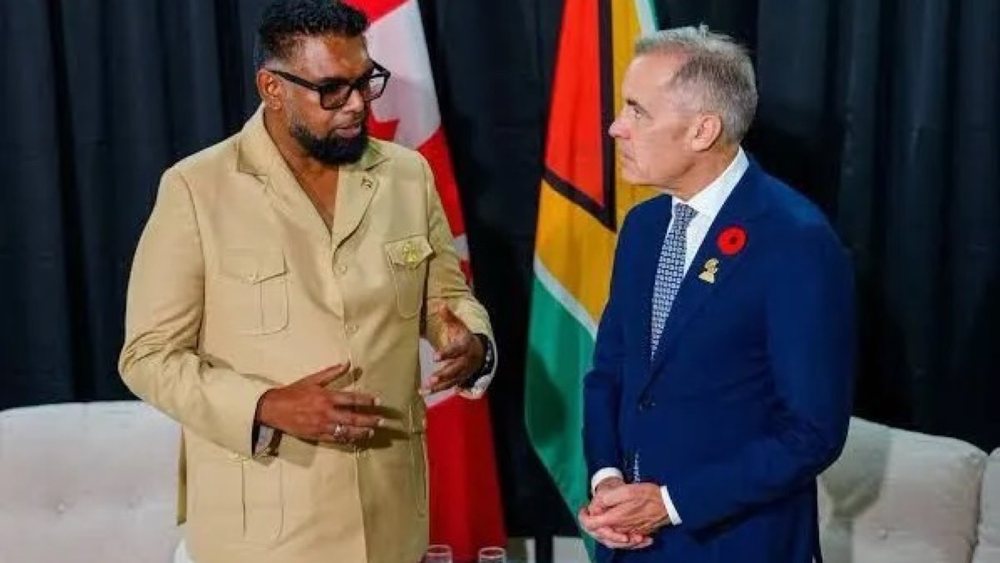
Canadian Prime Minister Mark Carney and Guyanese President Dr Mohamed Irfaan Ali have placed deeper economic cooperation—and a possible foreign investment promotion and protection agreement—on the bilateral agenda. The announcement is commercially significant, but it remains a policy signal rather than a completed treaty.
For investors, the immediate task is to understand what has been confirmed, what a future agreement could address and what remains unknown.
What the leaders actually announced
Carney and Ali met on the margins of the Commonwealth Heads of Government Meeting in Antigua and Barbuda. According to the official Canadian readout, they discussed opportunities to deepen cooperation in energy, mining, infrastructure and agriculture.
The leaders welcomed progress on a proposed framework for enhanced trade, investment and economic cooperation. They also explored opportunities for a potential Canada–Guyana foreign investment promotion and protection agreement, commonly known in Canada as a FIPA.
Those are related but distinguishable developments.
The wider framework could provide an umbrella for economic cooperation across several sectors. The potential FIPA would concern reciprocal rules governing covered investments and investors. The readout did not say the governments had formally launched treaty negotiations, agreed on a text or set a deadline for signature.
Guyana's official account of the meeting emphasised cooperation in trade, security, climate change, biodiversity and development finance. It likewise did not publish treaty terms or a timetable. Department of Public Information, Guyana.
A relationship with growing commercial weight
Canada's current country profile places bilateral merchandise trade at C$358.8 million in 2025, comprising C$59.4 million in Canadian exports to Guyana and C$299.4 million in Canadian imports from Guyana.
The headline total needs context. Gold accounted for C$283.1 million, or 94.6 per cent, of Canada's imports from Guyana. The Canadian direct-investment position in Guyana was reported at C$435 million in 2025. Global Affairs Canada's Canada–Guyana relations profile.
These figures show that the relationship has material economic scale. They do not, by themselves, show broad diversification across every sector. The concentration in gold makes the leaders' attention to energy, infrastructure and agriculture particularly relevant: a wider framework could support commercial engagement beyond the largest existing merchandise flow.
It would still be premature to treat the announcement as evidence that any specific project, financing facility or market-access concession has been approved.
What a FIPA is designed to do
Global Affairs Canada describes a FIPA as a bilateral reciprocal agreement intended to protect and promote foreign investment through legally binding rights and obligations.
Canada's current model, published in 2021 as the basis for future negotiations, contains provisions addressing matters such as:
- national treatment and most-favoured-nation treatment in defined circumstances;
- a minimum standard of treatment;
- protection against expropriation except under specified conditions;
- transfers of funds;
- transparency;
- investment promotion and facilitation;
- responsible business conduct;
- the governments' right to regulate for legitimate public-policy objectives; and
- procedures for investment disputes.
The model also contains reservations, exceptions and detailed provisions governing which investors and investments qualify for protection. Canada's 2021 Model FIPA.
That model is useful for understanding Canada's negotiating approach. It is not a draft Canada–Guyana treaty.
If negotiations proceed, the two governments would need to agree on the actual definitions, protections, exclusions, reservations, dispute provisions and institutional arrangements. The final balance could differ from the Canadian model.
A FIPA is not a free-trade agreement
The proposed investment agreement should not be confused with a free-trade agreement.
Canada's Trade Commissioner Service says Canada does not currently have a free-trade agreement with Guyana. A FIPA is designed around the treatment and protection of qualifying investments; it does not, by itself, eliminate customs duties, create product-specific rules of origin, open a tariff quota or guarantee access to government procurement.
Guyana already benefits from Canada's CARIBCAN programme, a non-reciprocal arrangement that provides eligible goods from participating Commonwealth Caribbean countries with preferential access to the Canadian market. That existing tariff treatment is separate from the investment-policy discussion announced by the two leaders.
For an exporter, the practical questions remain product-specific: tariff classification, origin, customs documentation, standards, import controls and the terms of any applicable preference. For an investor, the questions concern the legal entity, the investment, the domestic approvals and whatever protections a final treaty may eventually contain.
Keeping those tracks separate prevents a possible investment treaty from being presented as new tariff access that has not been announced.
Predictability is not the same as permission
A future investment treaty could give qualifying investors a clearer framework for assessing certain government-related risks. It would not replace the domestic approvals needed to establish or operate a project.
A Canadian investor in Guyana could still need corporate registration, sector licences, environmental approvals, land rights, tax compliance, immigration permissions and other authorisations applicable to the activity. Local-content obligations may remain relevant to petroleum-sector investments. Procurement rules and private contracts would continue to answer separate questions.
The same principle would apply to a qualifying Guyanese investor in Canada: treaty protection would not eliminate Canadian federal, provincial or sector-specific requirements.
A FIPA also would not guarantee that an investment will earn a profit, secure financing or survive poor execution. Market demand, costs, contractual allocation of risk, insurance, currency exposure and management capability remain commercial matters.
For project sponsors, the correct distinction is therefore between a legal framework that may improve predictability and the underlying business case that still has to work.
Coverage would depend on the final definitions
Even if a treaty is eventually signed, not every commercial relationship would automatically fall within it.
Investment agreements normally define who qualifies as an investor, what counts as a covered investment and how ownership or control is tested. They may contain sector reservations, tax or prudential exceptions, rules governing state enterprises and provisions dealing with investments made before entry into force.
Those details can be decisive for a group that invests through a subsidiary, joint venture, fund or intermediate holding company. The nationality of the operating company, the location of the asset and the structure of ownership may matter differently under the final text.
Companies should therefore avoid restructuring solely around an expected treaty benefit before the definitions and reservations are published. Corporate, tax, financing and regulatory decisions need their own commercial and professional analysis; a policy announcement cannot supply the missing legal terms.
Why the sector list matters
Energy, mining and infrastructure commonly require large upfront commitments and long operating periods. Agriculture can also involve land, processing facilities, logistics and long-term supply arrangements.
In these sectors, investors assess whether the rules applying to an asset may change during its life and how a dispute could be handled. A treaty may become one part of that assessment, alongside domestic law, licences, contracts and political-risk insurance.
However, the leaders' reference to these sectors does not identify priority projects or guarantee access to opportunities. Businesses should continue to evaluate individual projects on their own evidence.
The proposed wider economic framework could also matter independently of a FIPA. It may eventually provide mechanisms for government-to-government cooperation, commercial dialogue or sector promotion. Until its contents are published, its legal effect and practical functions remain unknown.
What businesses can do now
The announcement is strong enough to justify monitoring, but not strong enough to support treaty-dependent investment assumptions.
A company assessing a Canada–Guyana project can:
- identify the legal entity that would make and own the investment;
- map the licences, approvals and land or contractual rights required under existing law;
- distinguish project risk from risks that an investment treaty might address;
- avoid describing proposed protection as already available;
- record any treaty assumptions separately in the investment model; and
- monitor official Canadian and Guyanese releases for a negotiating launch, consultation or published text.
Existing investors should not assume that a future treaty would automatically cover every historical act or dispute. Coverage would depend on the final treaty's definitions, scope, temporal application and entry-into-force provisions.
Prospective investors should likewise avoid delaying all due diligence while waiting for an agreement that may take time to negotiate.
What to watch next
The next material confirmations would include:
- a formal announcement that negotiations have begun;
- publication of negotiating objectives or stakeholder consultations;
- clarification of the wider economic-cooperation framework;
- release of an agreed or signed treaty text;
- publication of reservations and sector exclusions;
- completion of the countries' respective approval procedures; and
- an official entry-into-force date.
Until those steps occur, the most accurate conclusion is measured: Canada and Guyana are exploring a potentially important investment-policy framework, but investors do not yet have a new bilateral treaty on which to rely.
The announcement matters because it establishes direction. Its commercial value will depend on the text that ultimately emerges—and on whether businesses continue to build viable projects under the laws that apply today.
Editor's note: This article is based on official information available on 5 November 2026. It is general investment intelligence and not legal advice.