Photo: Guyana Revenue Authority.
A shipment of imported spirits can move through several businesses before a bottle reaches the customer: from importer to distributor, from warehouse to wholesaler and finally onto a retailer's shelf.
At every stage, the bottle may look like ordinary inventory. But one small feature can determine whether that stock represents saleable merchandise or a significant compliance risk.
The Guyana Revenue Authority has renewed its warning that imported spirituous liquor must carry the required excise tax stamp. In its notice published on 3 November, the authority said unstamped products may be seized and that persons found holding them may face penalties, prosecution or other action under Guyana's customs and related laws.
The notice is relevant not only to the company that originally imported the product. GRA addressed importers, wholesalers and retailers, making clear that compliance risk can follow the product through the distribution chain.
For businesses, the central lesson is straightforward: buying imported spirits from another company does not remove the need to verify that the goods are compliant before accepting, stocking or selling them.
This is an enforcement reminder, not a new tax
The November notice does not announce a new excise tax, a new stamp regime or a new class of regulated product.
Guyana introduced its excise-stamp programme in November 2017 as an anti-smuggling and revenue-protection measure covering specified imported alcohol and tobacco products. GRA subsequently introduced three replacement alcohol-stamp designs in November 2025: one for duty-paid alcohol in containers up to and including 500 millilitres, another for duty-paid alcohol over 500 millilitres and a separate duty-free stamp.
The latest announcement should therefore be read as a renewed compliance warning under an established system.
That distinction matters. Businesses should not interpret the notice as creating a future obligation with an implementation period still to come. GRA's position is that the requirement already applies and that non-compliant goods may be seized.
The authority did not announce an amnesty, grace period or new deadline in the 3 November notice. It urged businesses that may not be fully compliant to visit GRA headquarters and regularise their affairs.
What the regulations cover
Regulation 212 of the Customs Regulations, made under the Customs Act, Chapter 82:01, establishes the excise stamp and identifies the imported products to which the requirement applies.
The listed alcohol categories are classified under tariff headings 22.04, 22.05, 22.07 and 22.08. They include specified wines, vermouth and other flavoured wines, ethyl alcohol, spirits, liqueurs and other spirituous beverages.
GRA's published programme guidance says foreign beer is excluded from the excise-stamp programme. The 3 November warning itself is specifically directed at imported spirituous liquor.
The regulations also provide for limited exemptions or authorisations approved through the statutory process. A business should not assume that an exception applies without written confirmation from GRA.
Businesses should not determine coverage solely by a product's everyday name. Customs obligations depend on the relevant tariff classification and the current regulatory treatment of the goods. An importer uncertain about classification or stamp requirements should obtain clarification from GRA or an appropriately qualified customs professional before committing capital to a shipment.
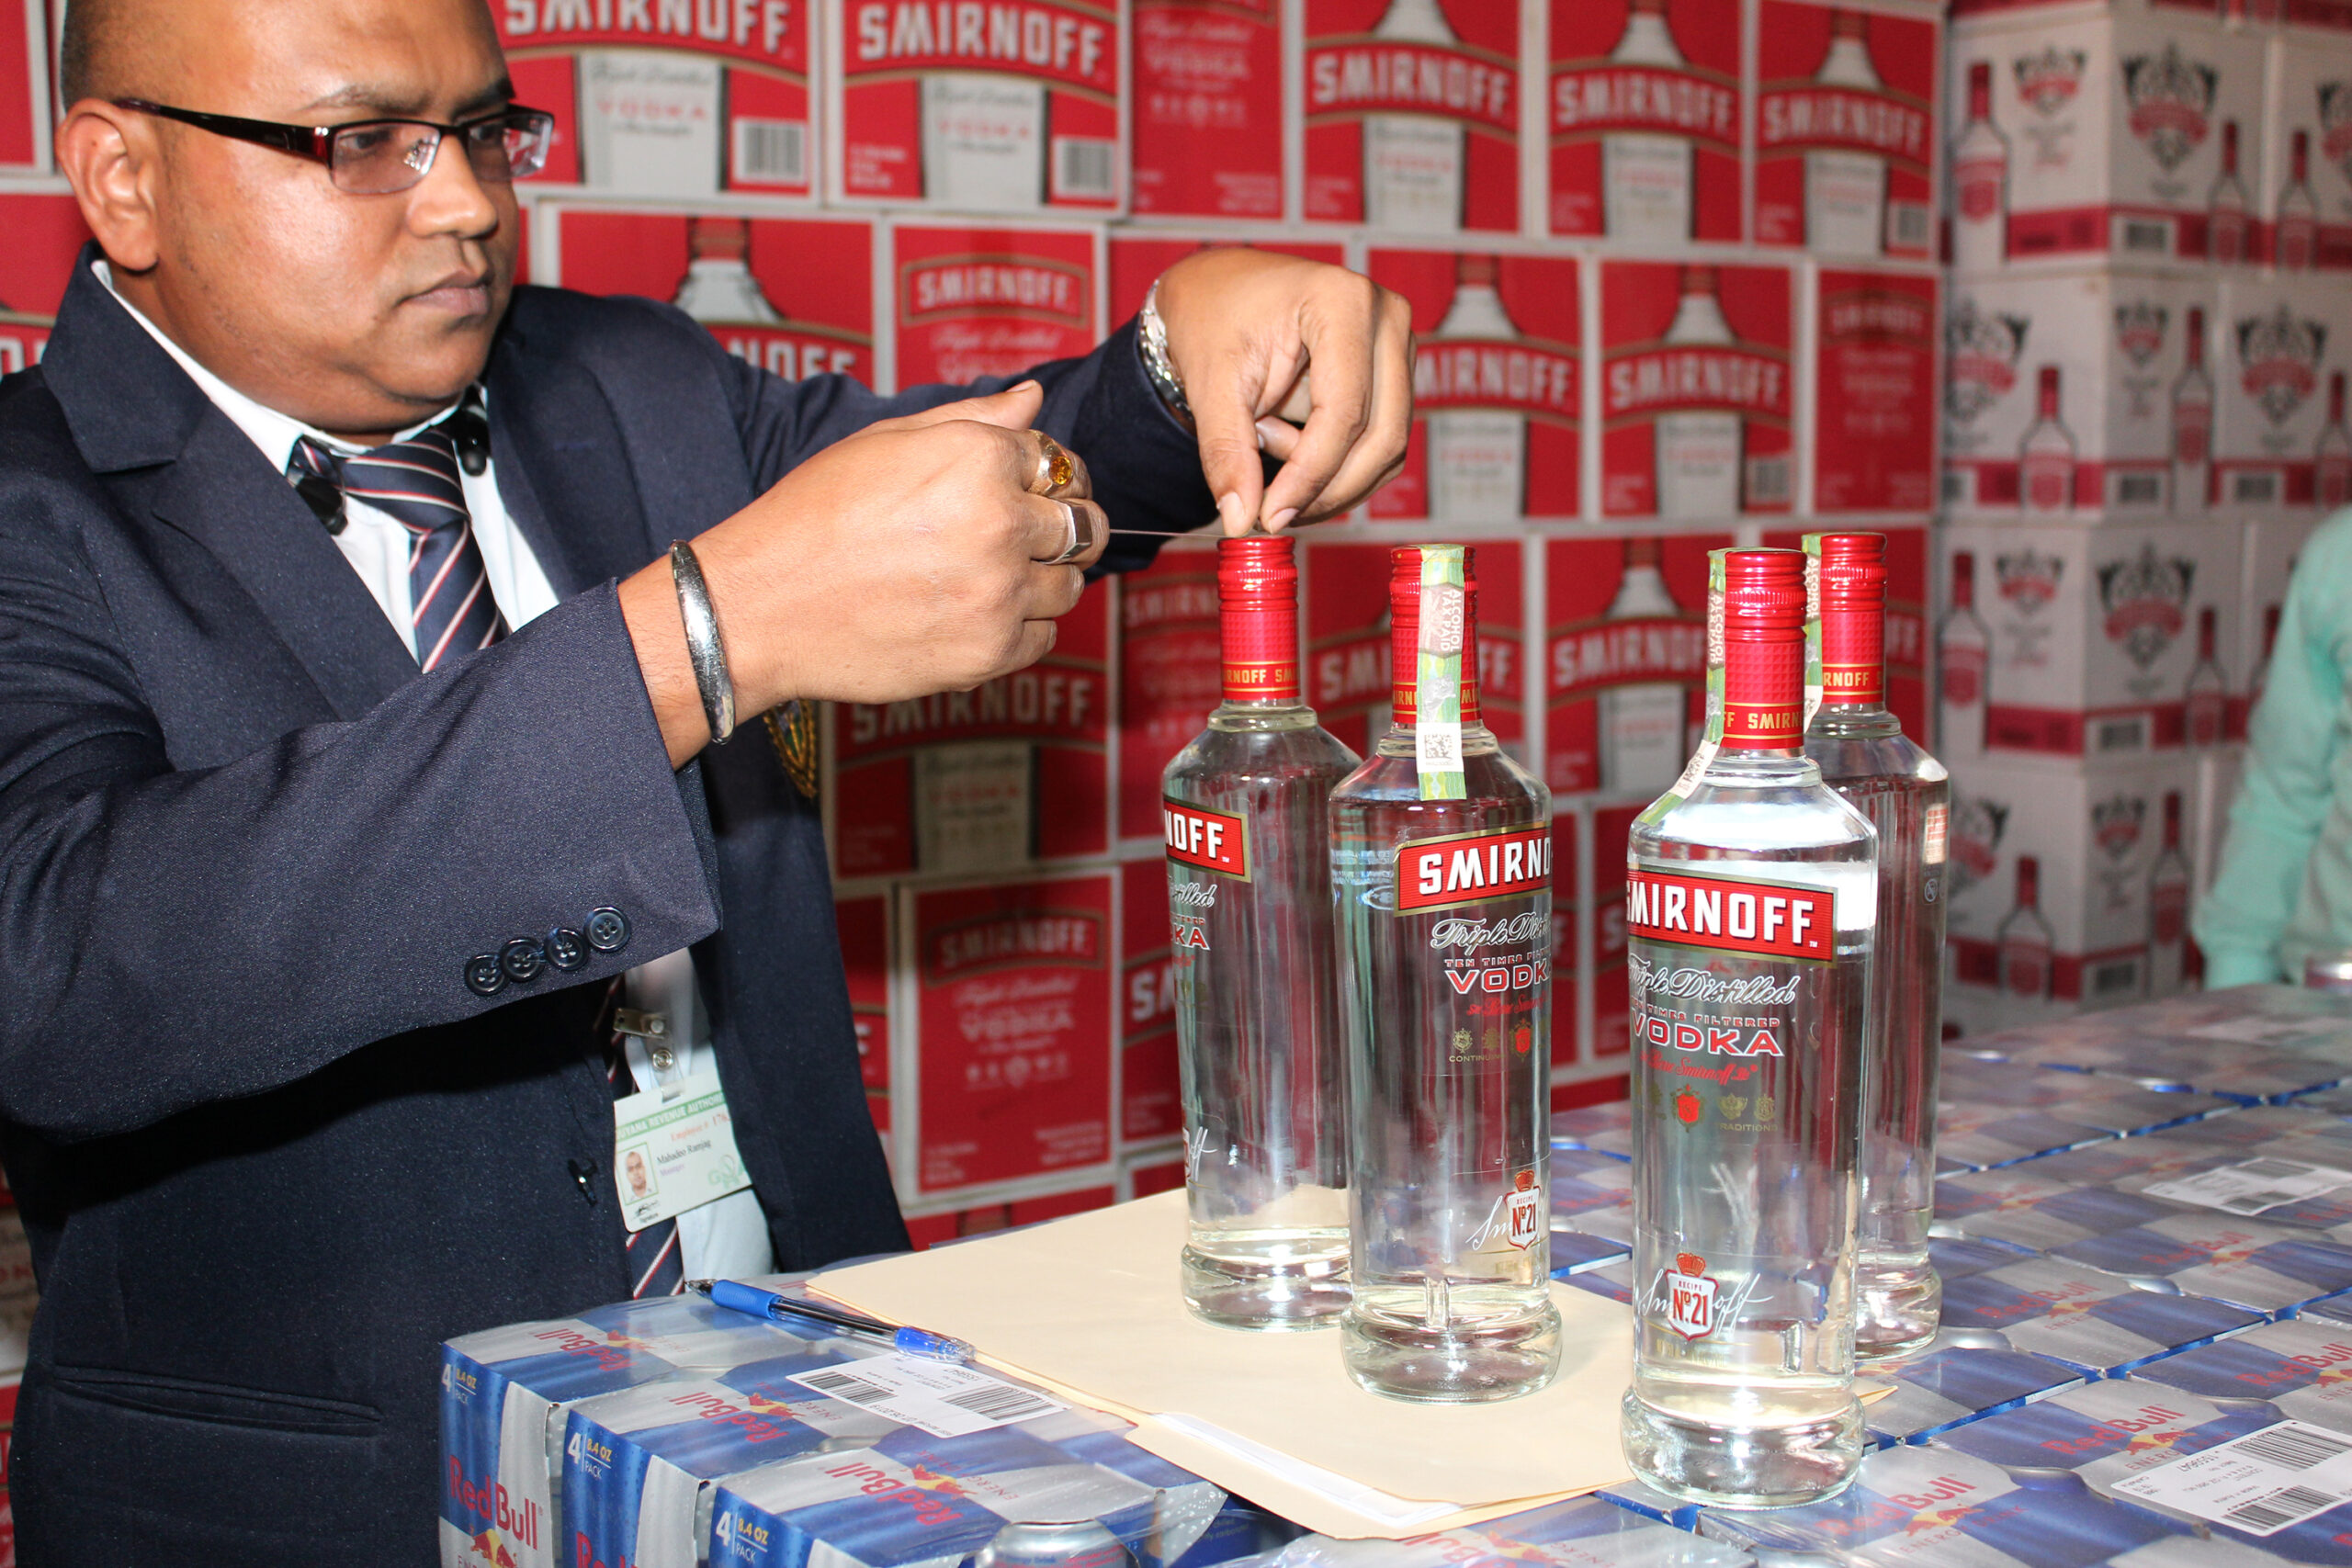
The rules also go further than simply requiring a label somewhere on the package. Regulation 213 says the stamp must be clearly visible when the product is displayed for sale and attached so that it is damaged or destroyed when the product is opened or an attempt is made to remove the stamp.
GRA's programme guidance describes the alcohol stamp as being applied over the bottle seal in an "L" shape. The commercial purpose is clear: a stamp should not be transferable from one product to another without evidence of interference.
Compliance risk extends beyond the importer
The importer sits at the beginning of the domestic supply chain, but the latest warning expressly includes wholesalers and retailers.
That is consistent with Regulation 220, which identifies possession of unstamped goods not destined for export as an offence. The regulations also address importing without registration, failing to affix stamps securely, defacing stamps, obtaining stamps without authority, making unauthorised stamps and attempting to reuse stamps.
Goods connected to an offence may be forfeited to the state under the applicable provisions of the Customs Act.
This creates a practical due-diligence issue for distributors, supermarkets, bars, hotels, restaurants, duty-free operators and independent retailers. A business that did not import a bottle may still be exposed if it accepts and holds non-compliant inventory.
An invoice by itself does not demonstrate that the physical product carries the required stamp. Equally, the presence of a label that resembles a stamp does not establish that it is genuine, correctly applied or linked to a compliant importation.
Each business handling imported spirits therefore has a reason to confirm both the legitimacy of its supplier and the condition of the goods received.
What importers are expected to control
The Customs Regulations impose additional obligations on manufacturers and importers beyond the physical stamp.
A person importing goods that require excise stamps must be registered in the manner prescribed by the Commissioner-General. The importer must apply for the stamps through the approved process and pay for them in the manner determined by GRA.
The regulations permit stamps, with prior approval, to be attached in a bonded warehouse, another approved place in Guyana or an approved location overseas.
Importers and manufacturers must also maintain records of stamp use and provide those records when required. Regulation 219 requires a monthly reconciliation statement showing stamps brought forward, issued, used and spoiled or damaged. The statement is due no later than 15 days after the end of the month in which the excise duty became payable.
These controls make the stamp part of a wider audit trail. The physical mark on the bottle is the visible end of a process that also involves customs classification, tax payment, authorised stamp procurement, controlled application and inventory reconciliation.
A company assessing an importer or distribution partner should therefore look beyond whether the supplier can deliver the required quantity. It should consider whether the supplier has a credible customs-compliance system and can provide appropriate commercial and import documentation.
A practical control system for wholesalers and retailers
GRA's notice does not prescribe a complete internal-control manual for downstream businesses. The following measures are therefore prudent commercial controls, not a substitute for legal or customs advice.
A wholesaler or retailer can begin by maintaining an approved-supplier list. Before onboarding a supplier, the buyer should establish the supplier's legal identity, business address and authority to distribute the products being offered.
Purchase orders and invoices should identify the supplier and products with enough detail to support traceability. Receiving staff should compare the physical shipment with the purchasing documents and inspect the bottles before the stock enters saleable inventory.
A useful receiving check can include:
- whether the product is imported and falls within the relevant alcohol category;
- whether the required stamp is present and clearly visible;
- whether the stamp crosses the seal in the expected manner;
- whether the stamp appears damaged, altered, reused or inconsistent with the container;
- whether the quantity and product description match the invoice; and
- whether the supplier can resolve discrepancies promptly.
Questionable inventory should be separated from ordinary stock while the business seeks clarification. It should not be placed on a shelf simply because a delivery has already been paid for or because the product came through a familiar intermediary.
Businesses with several branches should apply the same receiving standard across every location. A compliant head-office warehouse does not remove risk if a branch can accept goods directly from an unverified supplier.
Why the issue is commercial, not merely administrative
Excise-stamp compliance can affect more than the payment of tax.
Seized inventory can create a direct loss. An investigation may interrupt trading, tie up management time and require the business to reconstruct purchasing and stock records. A retailer may also need to remove related products from sale while their status is checked.
For hotels, restaurants, bars and event operators, unavailable beverage stock can disrupt customer service and planned functions. Importers and distributors may face delayed orders, damaged customer relationships and higher working-capital pressure if inventory cannot move normally.
There is also reputational risk. Businesses selling premium imported products depend on customers trusting that those products are authentic, properly sourced and safe. Association with illicit or unstamped goods can undermine that confidence even where the business did not manufacture or originally import the product.
A stronger control system therefore protects both regulatory compliance and the commercial value of the brand.
What the latest notice does not establish
The GRA notice does not report the number or value of recent seizures. It does not identify particular businesses, brands or planned enforcement locations.
It also does not announce a change to alcohol tax rates, stamp prices, tariff classifications or the underlying Customs Regulations.
Businesses should avoid treating the warning as evidence that a specific enforcement operation has begun unless GRA provides further information. They should equally avoid assuming that the absence of new operational details reduces the existing obligation.
GRA's message is narrower and more immediate: imported spirituous liquor must carry the required stamp, and businesses holding non-compliant goods face enforcement consequences.
The investor takeaway
For an investor entering Guyana's beverage, hospitality, retail or distribution market, customs compliance should be built into the operating model before inventory is purchased.
That means identifying who will act as importer of record, how products will be classified, where stamps will be obtained and applied, how stock will be reconciled and what evidence downstream buyers will receive.
For an existing operator, the 3 November notice is a reason to review suppliers and inspect current inventory rather than wait for a problem to arise.
A small stamp can represent a much larger compliance chain. The businesses best protected are those that can trace their products, verify their suppliers and demonstrate that controls operate from importation to the point of sale.
Businesses requiring clarification can consult GRA's 3 November notice and Excise Stamp Control Programme. The authority's notice directs businesses to its headquarters and lists 227-6060, extensions 3201–3210, for additional information.
This article provides general business information and does not constitute legal, tax or customs advice. Companies should confirm the current requirements applicable to their products and transactions directly with the Guyana Revenue Authority or a qualified adviser.