Photo: Department of Public Information / Office of the President
The Guyana Development Bank has received an estimated 15,000 to 20,000 applications since it began operating on October 5, giving the new institution an immediate test of its ability to assess business proposals and move viable applicants from interest to financing.
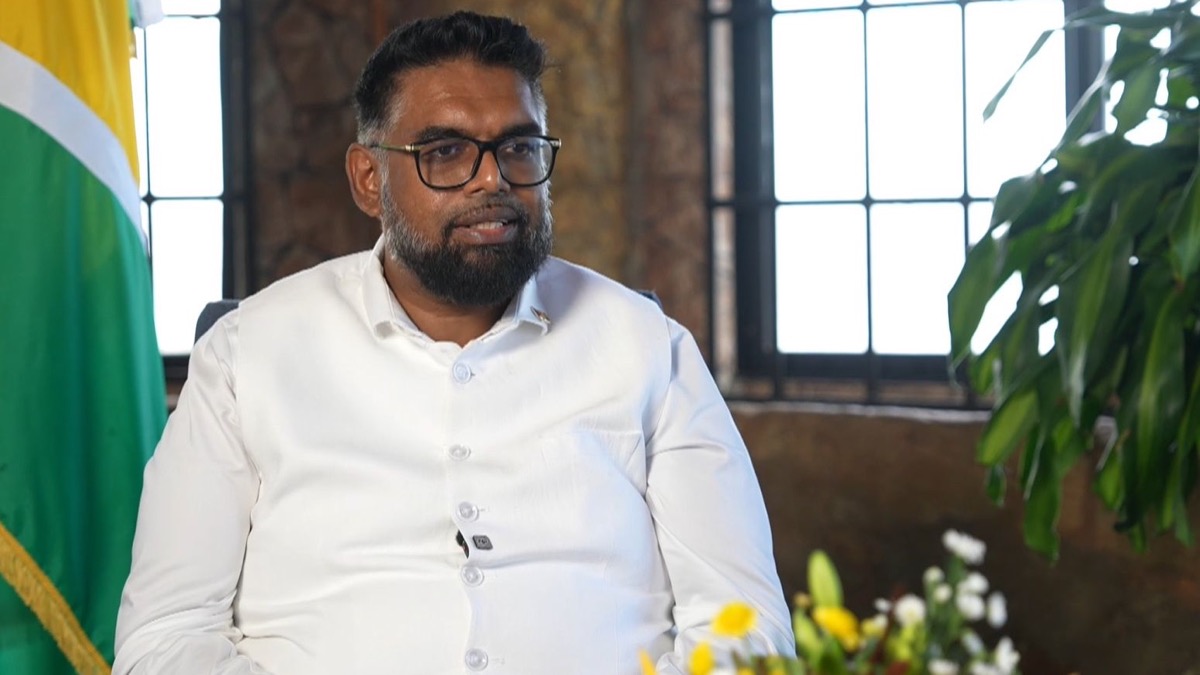
President Dr Mohamed Irfaan Ali disclosed the preliminary range on October 20, according to an official government report. He said applications are being evaluated and classified according to the sectors in which applicants intend to invest.
The number is significant because the bank was created to widen access to finance for entrepreneurs and small and medium-sized enterprises that may struggle to meet conventional collateral requirements. It should nevertheless be read carefully. The government described the figure as an estimate, and no accompanying breakdown was published showing completed applications, approvals, rejected submissions, sector distribution or funds disbursed.
The early total therefore measures demand at the top of the financing pipeline. The next stage will show how much of that demand can be converted into bankable businesses.
A digital opening creates a large first pipeline
The Development Bank began operating through an online portal designed to reduce the need for applicants to queue at a physical office. At launch, the government said applicants could register using an electronic identification card or passport number, while physical assistance would also be made available for people who require support.
The application requirements vary with the size of the proposed loan. The official launch guidance said applicants seeking between G$50,000 and G$300,000 would provide basic identifying information. Requests above G$300,000 and up to G$3 million require more detailed information about the proposed use of the financing, including a business proposal or plan.
That graduated model is intended to make smaller applications relatively simple while applying more scrutiny to larger requests. With as many as 20,000 submissions now reported, processing capacity becomes central. A digital intake system can collect applications quickly, but the bank must still verify identities, assess the commercial logic of proposals, evaluate repayment capacity and decide how to prioritise limited capital.
The government has not yet published an expected approval rate or a service standard for the time between application, decision and disbursement. Those measures will matter to entrepreneurs planning stock purchases, equipment orders or other time-sensitive investments.
What the bank is offering
The government’s October 5 launch release said the institution would provide loans of up to G$3 million to eligible small and medium-sized enterprises across all ten regions, without collateral and without interest.
Budget 2026 allocated US$100 million—reported by the government as just over G$20 billion—as the initial injection into the bank. The institution has authorised share capital of G$40 billion, according to the announcement of its inaugural board.
The financing is structured as credit rather than a grant. Borrowers will therefore be expected to repay, and the government has positioned successful repayment as a way for entrepreneurs to establish a credit history and eventually move into the conventional financial system.
The bank is also intended to pair financing with mentorship, business planning and technical guidance. That component could be as important as the loan terms. Removing interest and collateral lowers two major entry barriers, but it does not eliminate commercial risk, weak record-keeping, insufficient market demand or poor cash-flow management.
What the application surge tells investors
The estimated volume points to pent-up demand among Guyanese seeking capital to start or expand businesses. It also suggests that digital delivery can reach a large national audience quickly when the financial terms are attractive and the application threshold is accessible.
For the wider private sector, the pipeline could generate demand for bookkeeping, business-plan preparation, equipment, technology, packaging, logistics and professional services. If financing reaches commercially sound enterprises, the programme could also broaden the supplier base available to larger companies operating in Guyana.
However, application volume is not the same as investable demand. A credible assessment of the programme will require information on the quality of proposals, the sectors receiving finance, regional distribution, average loan size and the share of applicants that progress to approval.
The bank will also need to balance speed with sound credit administration. Processing applications too slowly would weaken the value of the programme, while approving them without adequate evaluation could expose public capital and borrowers to avoidable risk.
Governance and performance will shape the outcome
The Guyana Development Bank Act came into operation on October 5. Its seven-member inaugural board is chaired by Abu Zaman, with Kathy Smith as deputy chairperson. The government said on October 20 that the board was still considering candidates for chief executive officer and expected an appointment soon.
The legal framework requires the bank’s financial records to be examined annually by the Auditor General and an annual report on its operations to be prepared and presented to the National Assembly, according to the commencement announcement.
Those reports should eventually provide a more reliable basis for judging performance than launch-period application numbers. Investors and business organisations will be looking for transparent data on approvals, turnaround times, disbursements, sector exposure, repayment and arrears, as well as evidence that technical support is reaching borrowers.
What to watch next
The first decision and disbursement data will show whether the bank can turn a large digital pipeline into responsibly financed enterprises. Sector and regional breakdowns will indicate whether the programme is reaching productive activity throughout Guyana, while repayment performance will test whether the model is building durable businesses and credit histories.
The reported 15,000 to 20,000 applications represent an encouraging opening measure of interest. They are not yet evidence of 20,000 financed businesses. The Development Bank’s economic impact will depend on what happens after an entrepreneur presses “submit”: disciplined assessment, useful support, timely financing and sustainable repayment.